Bank-Owned Abandoned Homes: What Really Happens Next
Las casas abandonadas propiedad de los bancos - ¡Más información! 🏚️✨
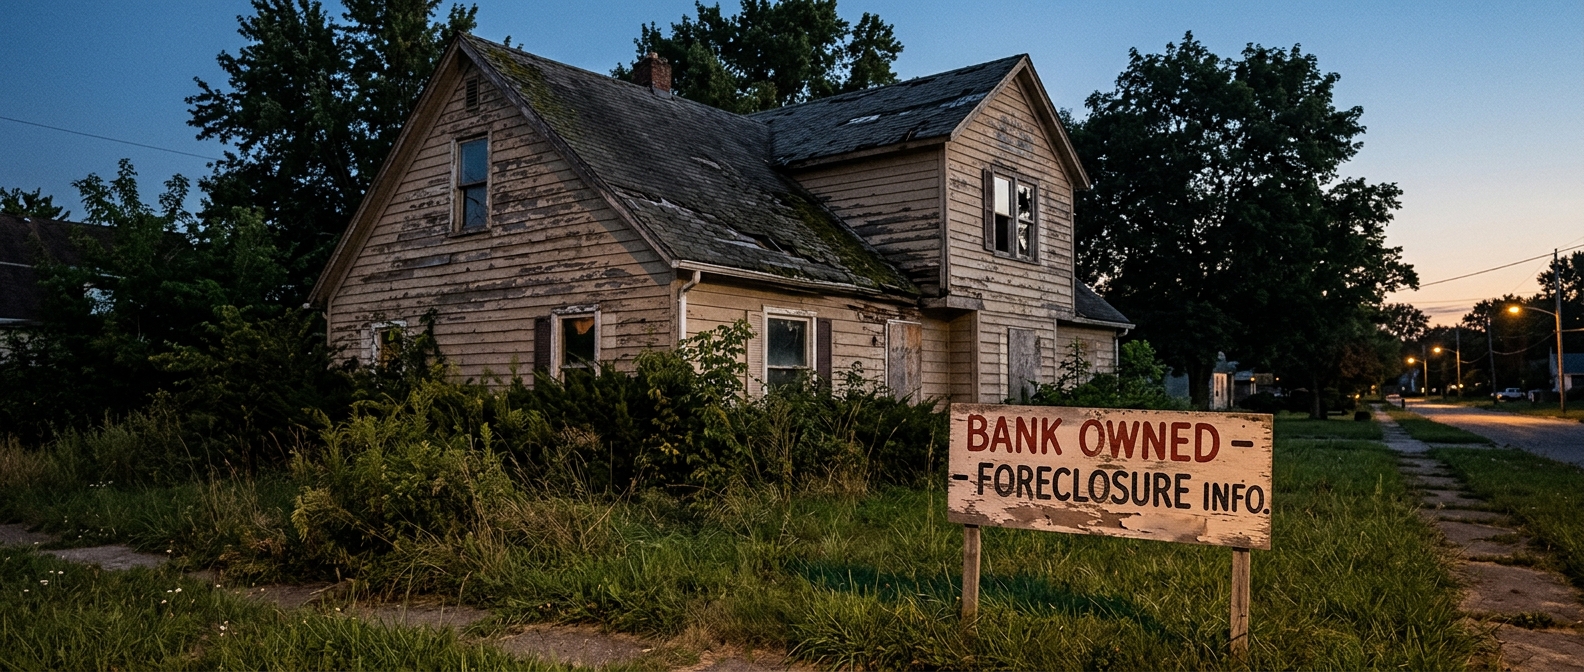
Drive through almost any town and you'll spot one: a house with boarded windows, an overgrown lawn, and a faded sign stuck in the dirt. These aren't just eyesores. Many of these abandoned properties are quietly owned by banks, sitting empty after a foreclosure nobody talks about. Behind every one of these houses is a paper trail, a price tag, and often, a surprising opportunity for someone willing to look closer.
Why Banks End Up Owning Empty Houses
When a homeowner stops paying their mortgage, the lender eventually forecloses. If nobody buys the home at auction, it reverts back to the bank. This is called an REO property, short for "real estate owned."
Banks aren't in the business of managing houses. They're in the business of lending money. So once a property becomes REO, it often sits untouched for months, sometimes years, while paperwork, legal reviews, and internal processes slowly move forward.
That delay is exactly why so many of these homes look abandoned. Nobody's mowing the lawn. Nobody's fixing the leaky roof. The bank is simply waiting.
The Old Way of Finding These Homes No Longer Works
A decade ago, buyers would drive neighborhoods looking for telltale signs: tall grass, newspapers piling up, or a foreclosure notice taped to a door. That approach wasted gas, time, and energy with no guarantee of success.
Today, that strategy barely scratches the surface. Most bank-owned inventory is tracked digitally, listed internally, or routed through specific asset management companies before it ever becomes publicly visible. Relying on windshield tours means missing the vast majority of real opportunities.
Why These Properties Can Be a Hidden Opportunity
Banks don't want to hold onto property. Every month a house sits empty, it costs them money in taxes, insurance, and maintenance. That pressure often translates into motivated sellers.
Here's what tends to make bank-owned homes appealing:
- Prices are frequently set below market value to move inventory faster.
- Banks are usually willing to negotiate once a property has lingered unsold.
- Many of these listings aren't heavily marketed, meaning less competition from other buyers.
- Some homes only need cosmetic work, not structural repairs, despite their abandoned appearance.
Of course, not every bank-owned home is a hidden gem. Some require serious renovation. That's why knowing what you're looking at matters just as much as knowing where to look.
What to Watch Out For
Before getting excited about a boarded-up bargain, it helps to understand the risks:
- Vacant homes can suffer from pipe damage, mold, or pest issues after months of neglect.
- Title issues sometimes linger from the foreclosure process itself.
- Local liens, like unpaid utility bills or code violation fines, can transfer with the property in some areas.
- Access for inspections may be limited until an offer is accepted.
None of this means these properties should be avoided. It just means due diligence is essential. A thorough inspection and a clear title search can save buyers from costly surprises down the road.
How the Process Usually Works
Buying a bank-owned property isn't dramatically different from a traditional purchase, but there are a few extra steps:
- The property is appraised and priced by the bank's asset managers.
- It's listed, sometimes publicly, sometimes through specialized REO marketing channels.
- Offers are submitted, often requiring proof of funds or pre-approval upfront.
- The bank reviews and negotiates, sometimes slower than a typical seller would.
- Once accepted, standard inspections, appraisals, and closing procedures follow.
Patience matters here. Banks move at their own pace, and offers can take longer to receive a response than they would with an individual seller.
Where the Real Opportunities Are Hiding
While understanding the general process is useful, the real value lies in specifics. Bank-owned inventory varies enormously by region, by lender, and even by neighborhood. A property that's been sitting for eight months in one state might be snapped up in days somewhere else. This is exactly why generic advice only goes so far. The most current listings, local pricing trends, and which banks are actively offloading inventory in a given area change constantly. Buyers who want a real shot at these properties typically need to look into local foreclosure listings, bank REO departments, and updated market data for their specific city or county.
Final Thoughts
Abandoned, bank-owned homes aren't just neglected houses. They're properties caught in a financial system that moves slowly and unevenly, creating pockets of opportunity for those who understand how it works. Whether the goal is a potential bargain or simply understanding why that empty house down the street looks the way it does, there's more going on behind those boarded windows than meets the eye. Exploring current local listings can reveal just how many of these opportunities are closer than expected.